Approved gratuity fund provisions remain deductible despite general actual-payment requirements, preventing revision of the allowed gratuity deduction...
Verification of intangible software expenditure and duplicated disallowances requires record-based reassessment before depreciation and income computa...
Cash receipt aggregation requires a single transaction, event or occasion; separate partner capital contributions cannot attract cash-receipt penaltie...
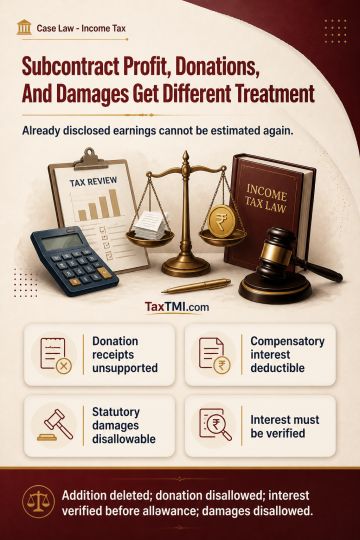
Profit on payments for subcontracted civil work cannot be separately estimated where the underlying contract receipts and profit have already been recorded, as this would duplicate disclosed profit; the related addition was deleted. A donation deduction remains disallowable where banking entries are unsupported by receipts. For delayed provident fund remittances, compensatory interest is deductible, whereas statutory damages for breach of payment obligations are penal and disallowable. The payment requires bifurcation between interest and damages, with the allowable interest component to be verified and permitted.
Profit on payments for subcontracted civil work cannot be separately estimated where the underlying contract receipts and profit have already been recorded, as this would duplicate disclosed profit; the related addition was deleted. A donation deduction remains disallowable where banking entries are unsupported by receipts. For delayed provident fund remittances, compensatory interest is deductible, whereas statutory damages for breach of payment obligations are penal and disallowable. The payment requires bifurcation between interest and damages, with the allowable interest component to be verified and permitted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932