Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
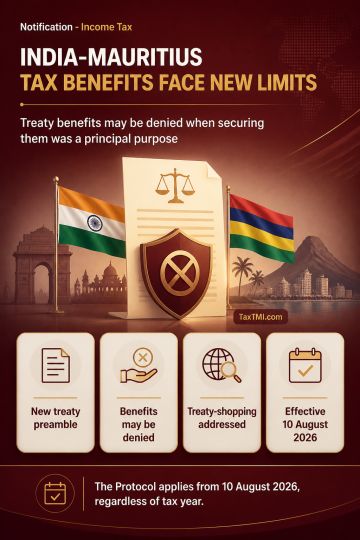
The India-Mauritius tax treaty Protocol replaces the treaty preamble to confirm that eliminating double taxation must not create opportunities for non-taxation or reduced taxation through tax evasion, avoidance, or treaty-shopping arrangements benefiting third-jurisdiction residents. It inserts an entitlement-to-benefits rule denying treaty relief where, considering all relevant facts and circumstances, obtaining the benefit was one of an arrangement's or transaction's principal purposes, unless granting relief accords with the relevant treaty provision's object and purpose. The Protocol entered into force on 10 August 2026 and applies from that date regardless of when tax is levied or the relevant taxable year.
The India-Mauritius tax treaty Protocol replaces the treaty preamble to confirm that eliminating double taxation must not create opportunities for non-taxation or reduced taxation through tax evasion, avoidance, or treaty-shopping arrangements benefiting third-jurisdiction residents. It inserts an entitlement-to-benefits rule denying treaty relief where, considering all relevant facts and circumstances, obtaining the benefit was one of an arrangement's or transaction's principal purposes, unless granting relief accords with the relevant treaty provision's object and purpose. The Protocol entered into force on 10 August 2026 and applies from that date regardless of when tax is levied or the relevant taxable year.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932