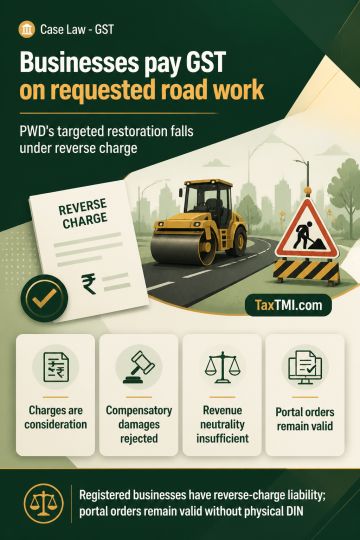
Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
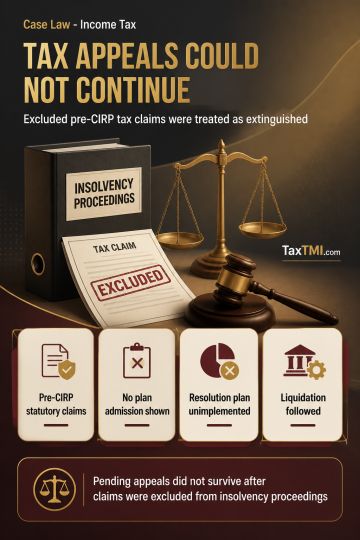
Pre-CIRP statutory income-tax claims not forming part of an approved resolution plan are treated as extinguished, preventing continuation of proceedings concerning those claims. This principle applies where a corporate debtor's successor entered the corporate insolvency resolution process, an approved resolution plan was not implemented, and liquidation followed. No material established admission of the Department's claims for the relevant assessment years in the resolution or liquidation proceedings; the connected Departmental appeals, assessee appeal, and cross-objection therefore did not survive.
Pre-CIRP statutory income-tax claims not forming part of an approved resolution plan are treated as extinguished, preventing continuation of proceedings concerning those claims. This principle applies where a corporate debtor's successor entered the corporate insolvency resolution process, an approved resolution plan was not implemented, and liquidation followed. No material established admission of the Department's claims for the relevant assessment years in the resolution or liquidation proceedings; the connected Departmental appeals, assessee appeal, and cross-objection therefore did not survive.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932