Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Double taxation of turnover requires holistic verification across separately registered units and permits limited rectification of overlapping assessm...
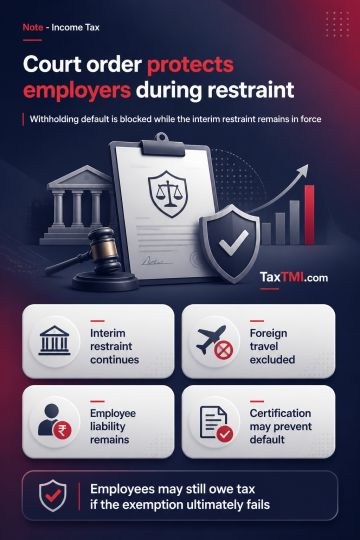
A subsisting interim direction prohibiting tax deduction from leave travel concession reimbursements prevents the employer from being treated as an assessee in default for the period covered by that restraint. This protection concerns the employer's withholding duty and does not make foreign-leg or circuitous travel eligible for the leave travel concession exemption, which remains confined to actual qualifying travel within India under the statutory conditions and prescribed limits. Employee tax liability may remain payable directly where the exemption ultimately fails. For periods without judicial protection, employers must examine travel eligibility and may avoid payer-default consequences only by establishing employee return filing, income inclusion and tax payment through the prescribed certification process.
A subsisting interim direction prohibiting tax deduction from leave travel concession reimbursements prevents the employer from being treated as an assessee in default for the period covered by that restraint. This protection concerns the employer's withholding duty and does not make foreign-leg or circuitous travel eligible for the leave travel concession exemption, which remains confined to actual qualifying travel within India under the statutory conditions and prescribed limits. Employee tax liability may remain payable directly where the exemption ultimately fails. For periods without judicial protection, employers must examine travel eligibility and may avoid payer-default consequences only by establishing employee return filing, income inclusion and tax payment through the prescribed certification process.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4923