Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Civil Court jurisdiction survives where the Tribunal cannot invalidate a registered sale deed affecting company property.
    Foreign-exchange adjudication writs fall within revenue matters, requiring placement before the court assigned that jurisdiction.
    Early-completion bonuses may survive force-majeure extensions, while unclaimed interest exceeds arbitration scope and GST requires component-wise asse...
    Transit-State GST Jurisdiction: Verification remains permissible, but external inter-State supplies lack a local detention-penalty nexus.
    Preferential-Issue Proceeds Must Follow Disclosed Objects; Later Ratification Cannot Cure Fraud or Unfair Trade Practices
    Section 195 withholding requires chargeable income: software use, technical services and business profits need separate treaty classification.
    Statutory cap on general GST penalties requires quashing excess penalties despite return filing and late-fee payment.
    Show cause notice limits GST demand grounds, requiring quashing where the final order relies on a different basis.
    Condonation of delay restored a GST appeal for merits review, subject to timely payment of costs.
    Prospective Baryte export restrictions preserve licensing control while requiring timely decisions on restricted-export authorisation applications.
    Title to liquidation assets depends on reliable company records; family consent terms without proof cannot establish ownership.
    SEZ de-notification rescinds the IT services zone notification while preserving prior acts and omissions under the SEZ framework.
    SEZ land de-notification releases designated parcels for domestic tariff area industrial development while reducing the notified zone's extent.
    Raw sugar tariff quota imports remain duty-free through the extended deadline, with all existing import conditions unchanged.
    Government securities exemption claims now require Form 173A disclosures for interest and capital gains under Schedule IV.
    Interest on Maharajah INR Bonds receives tax-deduction exemption for resident and foreign institutional holders, subject to reporting requirements.
    PSIC exemption for safe-country metallic scrap imports now covers eligible ICD clearances subject to entry-port verification.
    Raw sugar tariff rate quota holders receive extended deadline to surrender unutilised import allocations under existing conditions.
    Enhanced trade due diligence is advised for transactions involving a Bangladeshi firm following an unresolved quality-control complaint.
    Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Payment of the prescribed appellate pre-deposit and filing of an...

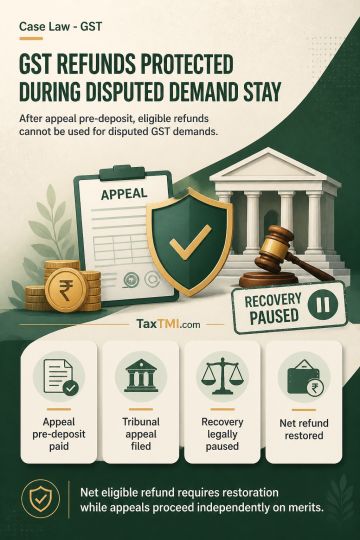
Statutory stay of GST recovery bars adjustment of eligible refunds against disputed demands after appellate pre-deposit.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

GST October 13, 2026 Case Laws HC
Payment of the prescribed appellate pre-deposit and filing of an appeal before the Tribunal trigger a deemed stay of recovery of the balance disputed GST demand under section 112(9), read with the CBIC Circular. During that statutory stay, net eligible GST refunds cannot be appropriated against the stayed demands. Appropriation of refunds for July to September 2023 against demands for financial years 2017-18 to 2019-20 was therefore impermissible, requiring restoration of the net eligible refund while the pending appeals proceed independently on merits.

Topics

Acts Income Tax