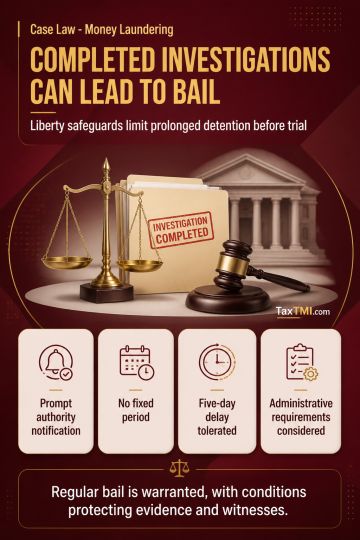
Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Page of 4935
Press 'Enter' after typing page number.
561 to 580 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Advance Pricing Agreement methodology may guide transfer-pricing...
Advance pricing agreement methodology can guide benchmarking for non-covered years when functions, assets, risks and activities remain materially unchanged.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Advance Pricing Agreement methodology may guide transfer-pricing benchmarking for an assessment year outside the agreement's term if the FAR analysis and underlying activities do not materially differ from covered years. Where Revenue challenges reliance on that methodology, it must establish the relevant factual distinction. A Transfer Pricing Officer who rejects the taxpayer's benchmarking in favour of the Other Method should apply that method and determine an arm's length price, rather than fixing a nil price on an ad hoc basis.
Advance Pricing Agreement methodology may guide transfer-pricing benchmarking for an assessment year outside the agreement's term if the FAR analysis and underlying activities do not materially differ from covered years. Where Revenue challenges reliance on that methodology, it must establish the relevant factual distinction. A Transfer Pricing Officer who rejects the taxpayer's benchmarking in favour of the Other Method should apply that method and determine an arm's length price, rather than fixing a nil price on an ad hoc basis.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935