Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
Advance pricing agreement methodology can guide benchmarking for non-covered years when functions, assets, risks and activities remain materially unch...
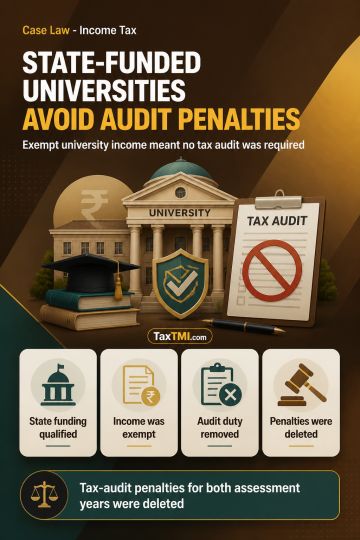
Tax-audit exemption for substantially State-funded educational universities prevents audit-failure penalties where income qualifies for statutory exem...
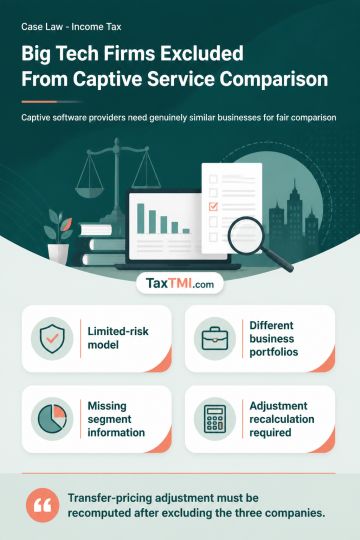
Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangemen...
Mobile-phone electronic evidence failed to establish customs undervaluation, while duty survived on non-authentic origin certificates without importer...
Automotive radio classification treats integrated infotainment features as supplementary, placing complete and qualifying unassembled units under the ...
Page of 4934
Press 'Enter' after typing page number.
661 to 680 of 98666 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
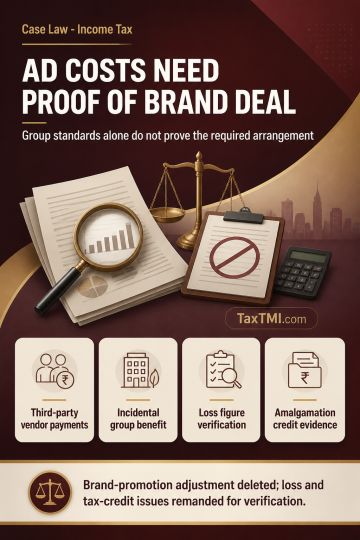
Advertisement and publicity expenditure paid to third-party vendors does not constitute a separate international transaction of brand-promotion services merely because group communication standards exist or an associated enterprise obtains an incidental benefit; an underlying arrangement or understanding must be established. The related transfer-pricing adjustment was deleted. Where an assessment order and computation sheet show differing carry-forward loss figures, the eligible loss requires verification against assessed income or loss and applicable law; limited recomputation was remanded. TDS/TCS credit after amalgamation depends on the transferee offering or being assessed on the corresponding income, subject to verification of amalgamation records, tax credit and supporting evidence; that claim was remanded.
Advertisement and publicity expenditure paid to third-party vendors does not constitute a separate international transaction of brand-promotion services merely because group communication standards exist or an associated enterprise obtains an incidental benefit; an underlying arrangement or understanding must be established. The related transfer-pricing adjustment was deleted. Where an assessment order and computation sheet show differing carry-forward loss figures, the eligible loss requires verification against assessed income or loss and applicable law; limited recomputation was remanded. TDS/TCS credit after amalgamation depends on the transferee offering or being assessed on the corresponding income, subject to verification of amalgamation records, tax credit and supporting evidence; that claim was remanded.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934