Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Income of a substantially State-funded educational university...
Tax-audit exemption for substantially State-funded educational universities prevents audit-failure penalties where income qualifies for statutory exemption.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
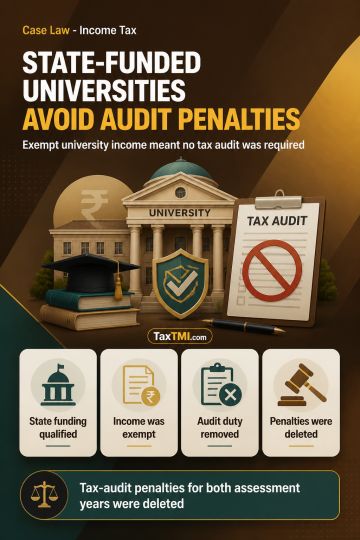
Income of a substantially State-funded educational university was exempt under section 10(23C)(iiiab), removing the requirement for a tax audit under section 44AB. As the audit obligation did not apply, penalty under section 271B for failure to obtain an audit was inapplicable. Tax-audit penalties for both assessment years were therefore deleted.
Income of a substantially State-funded educational university was exempt under section 10(23C)(iiiab), removing the requirement for a tax audit under section 44AB. As the audit obligation did not apply, penalty under section 271B for failure to obtain an audit was inapplicable. Tax-audit penalties for both assessment years were therefore deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929