Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
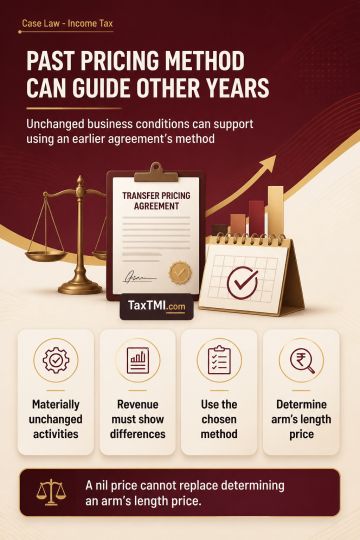
Advance pricing agreement methodology can guide benchmarking for non-covered years when functions, assets, risks and activities remain materially unch...
Tax-audit exemption for substantially State-funded educational universities prevents audit-failure penalties where income qualifies for statutory exem...
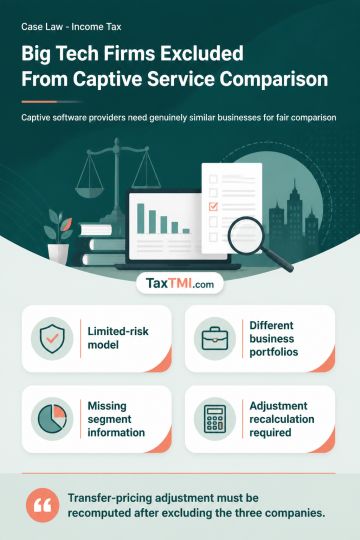
Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangemen...
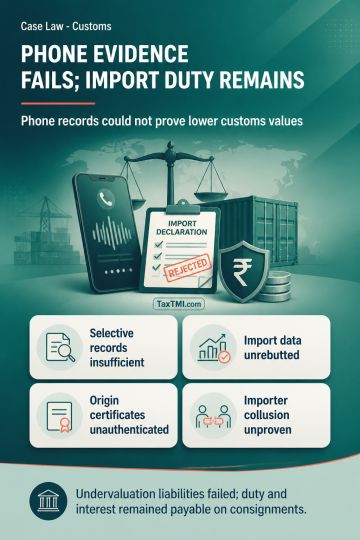
Mobile-phone electronic evidence failed to establish customs undervaluation, while duty survived on non-authentic origin certificates without importer...
Automotive radio classification treats integrated infotainment features as supplementary, placing complete and qualifying unassembled units under the ...
Page of 4934
Press 'Enter' after typing page number.
661 to 680 of 98666 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Functional, asset and risk analysis requires comparables for a...
Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangements.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Functional, asset and risk analysis requires comparables for a captive software development service provider to reflect its limited-risk, cost-plus operating model. Diversified technology companies with broad service portfolios, substantial brand value and intangibles, significant research and development, goodwill, patents, and different risk profiles are functionally dissimilar. The absence of standalone segmental information further impairs reliable comparison. Infosys Ltd., Wipro Ltd. and LTI Mindtree Ltd. are therefore unsuitable comparables, requiring recomputation of any transfer-pricing adjustment after their exclusion.
Functional, asset and risk analysis requires comparables for a captive software development service provider to reflect its limited-risk, cost-plus operating model. Diversified technology companies with broad service portfolios, substantial brand value and intangibles, significant research and development, goodwill, patents, and different risk profiles are functionally dissimilar. The absence of standalone segmental information further impairs reliable comparison. Infosys Ltd., Wipro Ltd. and LTI Mindtree Ltd. are therefore unsuitable comparables, requiring recomputation of any transfer-pricing adjustment after their exclusion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934