Jurisdictional sanction requirements bar reassessment when approval comes from an authority lacking statutory competence under the applicable framewor...
Recorded sales receipts cannot be reassessed as unexplained cash credits, eliminating the basis for consequential alleged commission expenditure addit...
Sufficient cause for delayed income-tax appeals requires bona fide diligence; unsubstantiated counsel illness and assessee inaction defeat condonation...
TNMM Segmentation Limits Transfer-Pricing Adjustments to Associated-Enterprise Transactions and Requires Turnover-Based Comparable Selection for IT Se...
Functional, asset and risk analysis requires comparables for a...
Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangements.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
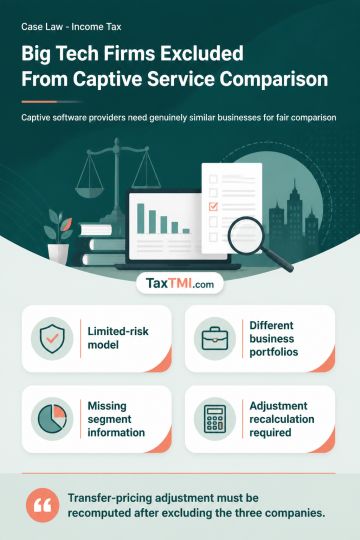
Functional, asset and risk analysis requires comparables for a captive software development service provider to reflect its limited-risk, cost-plus operating model. Diversified technology companies with broad service portfolios, substantial brand value and intangibles, significant research and development, goodwill, patents, and different risk profiles are functionally dissimilar. The absence of standalone segmental information further impairs reliable comparison. Infosys Ltd., Wipro Ltd. and LTI Mindtree Ltd. are therefore unsuitable comparables, requiring recomputation of any transfer-pricing adjustment after their exclusion.
Functional, asset and risk analysis requires comparables for a captive software development service provider to reflect its limited-risk, cost-plus operating model. Diversified technology companies with broad service portfolios, substantial brand value and intangibles, significant research and development, goodwill, patents, and different risk profiles are functionally dissimilar. The absence of standalone segmental information further impairs reliable comparison. Infosys Ltd., Wipro Ltd. and LTI Mindtree Ltd. are therefore unsuitable comparables, requiring recomputation of any transfer-pricing adjustment after their exclusion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI