Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangemen...
Mobile-phone electronic evidence failed to establish customs undervaluation, while duty survived on non-authentic origin certificates without importer...
Automotive radio classification treats integrated infotainment features as supplementary, placing complete and qualifying unassembled units under the ...
Separate corporate personality prevents directors from being personally liable for company deposits without a guarantee or independent legal undertaki...
Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
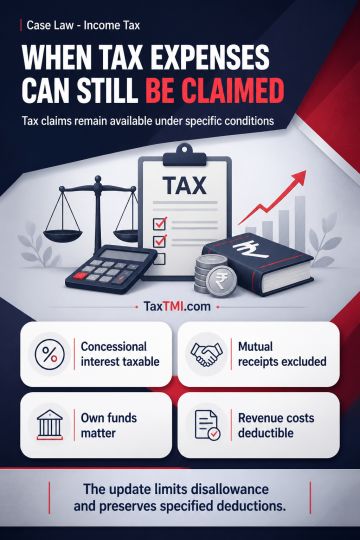
Concessional-rate interest remains taxable rather than exempt income, so expenditure relating to it is not subject to exempt-income disallowance. Interest between an Indian permanent establishment and its head office or overseas branches is a mutual receipt rather than income; related administrative expenditure is likewise outside that disallowance. Consistent year-end revaluation of outstanding foreign-exchange forward contracts under the mercantile system produces an allowable loss where an existing obligation and reliable estimation exist. Interest disallowance is unwarranted where interest-free own funds exceed exempt-income investments absent a borrowing nexus. Broken-period interest on banking securities and voluntary-retirement expenditure for workforce rationalisation are revenue deductions. Head-office and global-system charges require prior factual classification before withholding or royalty consequences are considered.
Concessional-rate interest remains taxable rather than exempt income, so expenditure relating to it is not subject to exempt-income disallowance. Interest between an Indian permanent establishment and its head office or overseas branches is a mutual receipt rather than income; related administrative expenditure is likewise outside that disallowance. Consistent year-end revaluation of outstanding foreign-exchange forward contracts under the mercantile system produces an allowable loss where an existing obligation and reliable estimation exist. Interest disallowance is unwarranted where interest-free own funds exceed exempt-income investments absent a borrowing nexus. Broken-period interest on banking securities and voluntary-retirement expenditure for workforce rationalisation are revenue deductions. Head-office and global-system charges require prior factual classification before withholding or royalty consequences are considered.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927