Unsigned third-party records cannot establish on-money payments without corroboration and cross-examination, requiring deletion of the related additio...
Service-tax exemptions for railway and Government works restrict de novo reassessment, while unsupported limitation and consultation failures invalida...
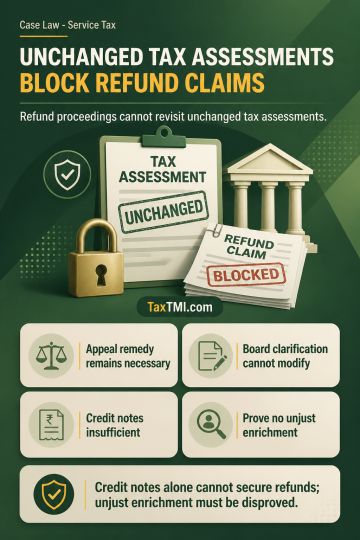
Service tax refund claims against unmodified self-assessments are not maintainable because self-assessment constitutes an assessment order and cannot be reviewed or reassessed through refund proceedings. A Board clarification on exemption eligibility, or a representation to the Board, cannot modify an assessment or replace the statutory appellate remedy. Post-clearance credit notes for housekeeping and canteen or outdoor catering services do not by themselves rebut the statutory presumption that the tax burden was passed on. Direct refund also requires proof that unjust enrichment has not occurred; adjustment provisions for service tax cannot override that requirement.
Service tax refund claims against unmodified self-assessments are not maintainable because self-assessment constitutes an assessment order and cannot be reviewed or reassessed through refund proceedings. A Board clarification on exemption eligibility, or a representation to the Board, cannot modify an assessment or replace the statutory appellate remedy. Post-clearance credit notes for housekeeping and canteen or outdoor catering services do not by themselves rebut the statutory presumption that the tax burden was passed on. Direct refund also requires proof that unjust enrichment has not occurred; adjustment provisions for service tax cannot override that requirement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927