Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
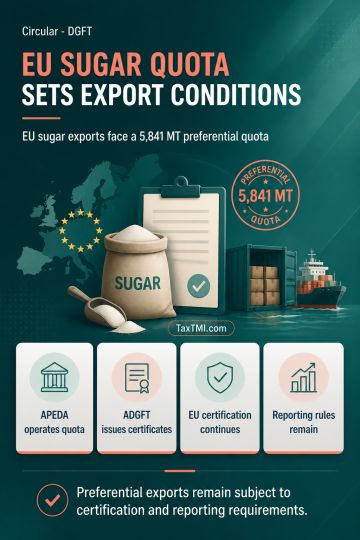
Sugar exports from India to the EU under the tariff-rate quota are allocated 5,841 MT for 2026-27 (October 2026 to September 2027). Export of sugar under the quota remains free, subject to applicable restrictions. Where preferential treatment requires a Certificate of Origin, ADGFT Mumbai must issue it on APEDA's recommendation of the eligible entity and quantity; EU-specific certification requirements continue to apply. APEDA will operate the quota, and existing reporting requirements remain applicable. The allocation period is stated inconsistently as 2025-26 in the allocation provision and 2026-27 in the stated effect.
Sugar exports from India to the EU under the tariff-rate quota are allocated 5,841 MT for 2026-27 (October 2026 to September 2027). Export of sugar under the quota remains free, subject to applicable restrictions. Where preferential treatment requires a Certificate of Origin, ADGFT Mumbai must issue it on APEDA's recommendation of the eligible entity and quantity; EU-specific certification requirements continue to apply. APEDA will operate the quota, and existing reporting requirements remain applicable. The allocation period is stated inconsistently as 2025-26 in the allocation provision and 2026-27 in the stated effect.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4936