Transfer-pricing aggregation of distinct support-service and subcontract transactions was rejected, while debt-free receivables attracted no notional ...
Customs exemptions cover photovoltaic assembly machinery and PVF backsheets, while fully declared cleared imports may avoid confiscation and penalties...
Specific tariff classification for LCD devices overrides treatment as electricity-meter parts, defeating differential duty, extended limitation, and p...
Stayed disciplinary punishment does not establish unfitness for insolvency professional registration; reconsideration must disregard mere pendency of ...
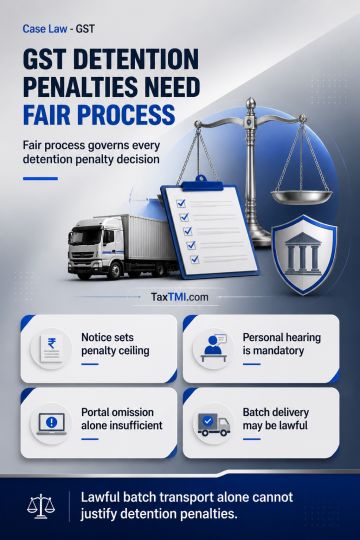
GST detention penalty proceedings require consideration of objections, a statutorily required personal hearing, and reasoned decision-making; an order issued on the notice date without these safeguards breaches natural justice. Section 75(7) bars confirmation of a penalty above the amount proposed in the show-cause notice, with any correction requiring timely disclosure. Failure to upload a Form GST MOV-09 order on the common portal does not alone invalidate proceedings. Under Rule 55(5), goods supplied under complete prior invoices may be transported in batches using a delivery challan; item-wise invoicing or absence of the original invoice does not itself establish tax evasion or justify detention penalty.
GST detention penalty proceedings require consideration of objections, a statutorily required personal hearing, and reasoned decision-making; an order issued on the notice date without these safeguards breaches natural justice. Section 75(7) bars confirmation of a penalty above the amount proposed in the show-cause notice, with any correction requiring timely disclosure. Failure to upload a Form GST MOV-09 order on the common portal does not alone invalidate proceedings. Under Rule 55(5), goods supplied under complete prior invoices may be transported in batches using a delivery challan; item-wise invoicing or absence of the original invoice does not itself establish tax evasion or justify detention penalty.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918