Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
Juridical seat versus arbitral venue determines supervisory court jurisdiction, while timely award challenges remain within the prescribed limitation ...
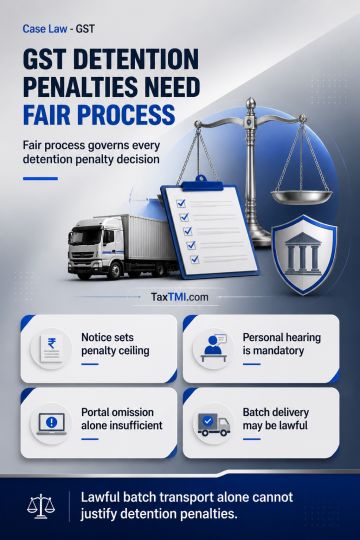
GST detention penalty proceedings require consideration of objections, a statutorily required personal hearing, and reasoned decision-making; an order issued on the notice date without these safeguards breaches natural justice. Section 75(7) bars confirmation of a penalty above the amount proposed in the show-cause notice, with any correction requiring timely disclosure. Failure to upload a Form GST MOV-09 order on the common portal does not alone invalidate proceedings. Under Rule 55(5), goods supplied under complete prior invoices may be transported in batches using a delivery challan; item-wise invoicing or absence of the original invoice does not itself establish tax evasion or justify detention penalty.
GST detention penalty proceedings require consideration of objections, a statutorily required personal hearing, and reasoned decision-making; an order issued on the notice date without these safeguards breaches natural justice. Section 75(7) bars confirmation of a penalty above the amount proposed in the show-cause notice, with any correction requiring timely disclosure. Failure to upload a Form GST MOV-09 order on the common portal does not alone invalidate proceedings. Under Rule 55(5), goods supplied under complete prior invoices may be transported in batches using a delivery challan; item-wise invoicing or absence of the original invoice does not itself establish tax evasion or justify detention penalty.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916