Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Page of 4915
Press 'Enter' after typing page number.
681 to 700 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
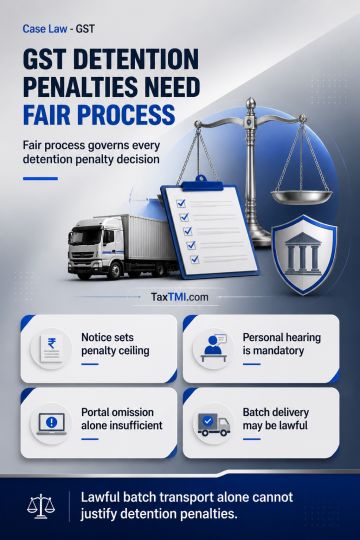
GST detention penalty proceedings require consideration of objections, a statutorily required personal hearing, and reasoned decision-making; an order issued on the notice date without these safeguards breaches natural justice. Section 75(7) bars confirmation of a penalty above the amount proposed in the show-cause notice, with any correction requiring timely disclosure. Failure to upload a Form GST MOV-09 order on the common portal does not alone invalidate proceedings. Under Rule 55(5), goods supplied under complete prior invoices may be transported in batches using a delivery challan; item-wise invoicing or absence of the original invoice does not itself establish tax evasion or justify detention penalty.
GST detention penalty proceedings require consideration of objections, a statutorily required personal hearing, and reasoned decision-making; an order issued on the notice date without these safeguards breaches natural justice. Section 75(7) bars confirmation of a penalty above the amount proposed in the show-cause notice, with any correction requiring timely disclosure. Failure to upload a Form GST MOV-09 order on the common portal does not alone invalidate proceedings. Under Rule 55(5), goods supplied under complete prior invoices may be transported in batches using a delivery challan; item-wise invoicing or absence of the original invoice does not itself establish tax evasion or justify detention penalty.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915