Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
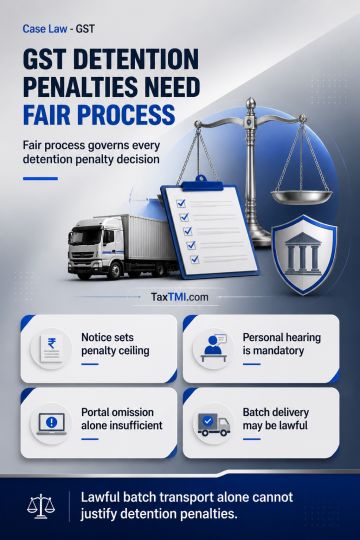
GST detention penalty proceedings require consideration of objections, a statutorily required personal hearing, and reasoned decision-making; an order issued on the notice date without these safeguards breaches natural justice. Section 75(7) bars confirmation of a penalty above the amount proposed in the show-cause notice, with any correction requiring timely disclosure. Failure to upload a Form GST MOV-09 order on the common portal does not alone invalidate proceedings. Under Rule 55(5), goods supplied under complete prior invoices may be transported in batches using a delivery challan; item-wise invoicing or absence of the original invoice does not itself establish tax evasion or justify detention penalty.
GST detention penalty proceedings require consideration of objections, a statutorily required personal hearing, and reasoned decision-making; an order issued on the notice date without these safeguards breaches natural justice. Section 75(7) bars confirmation of a penalty above the amount proposed in the show-cause notice, with any correction requiring timely disclosure. Failure to upload a Form GST MOV-09 order on the common portal does not alone invalidate proceedings. Under Rule 55(5), goods supplied under complete prior invoices may be transported in batches using a delivery challan; item-wise invoicing or absence of the original invoice does not itself establish tax evasion or justify detention penalty.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902