Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
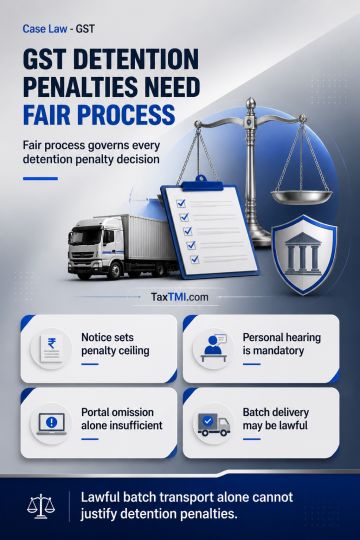
GST detention penalty proceedings require consideration of objections, a statutorily required personal hearing, and reasoned decision-making; an order issued on the notice date without these safeguards breaches natural justice. Section 75(7) bars confirmation of a penalty above the amount proposed in the show-cause notice, with any correction requiring timely disclosure. Failure to upload a Form GST MOV-09 order on the common portal does not alone invalidate proceedings. Under Rule 55(5), goods supplied under complete prior invoices may be transported in batches using a delivery challan; item-wise invoicing or absence of the original invoice does not itself establish tax evasion or justify detention penalty.
GST detention penalty proceedings require consideration of objections, a statutorily required personal hearing, and reasoned decision-making; an order issued on the notice date without these safeguards breaches natural justice. Section 75(7) bars confirmation of a penalty above the amount proposed in the show-cause notice, with any correction requiring timely disclosure. Failure to upload a Form GST MOV-09 order on the common portal does not alone invalidate proceedings. Under Rule 55(5), goods supplied under complete prior invoices may be transported in batches using a delivery challan; item-wise invoicing or absence of the original invoice does not itself establish tax evasion or justify detention penalty.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899