Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
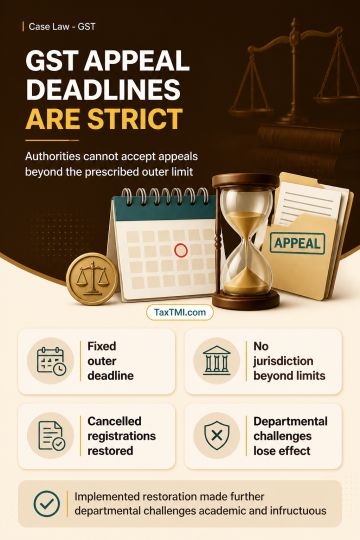
Statutory limits on condonation of delay confine the First Appellate Authority's jurisdiction in GST registration-cancellation appeals. Extraordinary equitable relief available in constitutional jurisdiction cannot expand a statutory appellate authority's power or permit condonation beyond the prescribed outer limit; appeals entertained on that basis are without jurisdiction. However, where the Department has implemented the appellate orders by restoring cancelled GST registrations, it cannot seek their annulment without addressing the resulting legal and commercial consequences. Restoration renders departmental challenges ineffective, academic and infructuous, so no effective appellate relief remains available.
Statutory limits on condonation of delay confine the First Appellate Authority's jurisdiction in GST registration-cancellation appeals. Extraordinary equitable relief available in constitutional jurisdiction cannot expand a statutory appellate authority's power or permit condonation beyond the prescribed outer limit; appeals entertained on that basis are without jurisdiction. However, where the Department has implemented the appellate orders by restoring cancelled GST registrations, it cannot seek their annulment without addressing the resulting legal and commercial consequences. Restoration renders departmental challenges ineffective, academic and infructuous, so no effective appellate relief remains available.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897