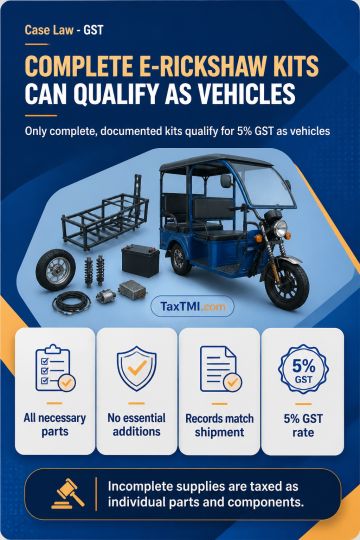
Complete e-rickshaw CKD kits fall under Rule 2(a) as finished electrically operated vehicles only where every component necessary for one vehicle is supplied together as one identifiable kit and assembly requires no additional essential component. Purchase orders, invoices, packing lists and contemporaneous records must consistently identify the supply as an e-rickshaw in CKD/SKD condition, and the consignment must match those records. On satisfying all four requirements, classification is under HSN 87038040 as a three-wheeled electrically operated vehicle, attracting 5% GST; otherwise, the supply is classified and taxed as individual parts and components.
Complete e-rickshaw CKD kits fall under Rule 2(a) as finished electrically operated vehicles only where every component necessary for one vehicle is supplied together as one identifiable kit and assembly requires no additional essential component. Purchase orders, invoices, packing lists and contemporaneous records must consistently identify the supply as an e-rickshaw in CKD/SKD condition, and the consignment must match those records. On satisfying all four requirements, classification is under HSN 87038040 as a three-wheeled electrically operated vehicle, attracting 5% GST; otherwise, the supply is classified and taxed as individual parts and components.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI