Composite supply of milling allocated wheat, fortifying the flour and packing it for Public Distribution System delivery has milling as its principal supply; fortification and packaging are ancillary. Total consideration includes cash and agreed non-cash consideration represented by retained gunny bags, bran and refractor, rather than their future disposal proceeds. Where goods used for fortification and packing remain within 25 per cent of total composite-supply value, the supply to the State Government qualifies for Serial No. 3A exemption because it relates to public distribution, a function under Article 243G. If the goods component exceeds that threshold, exemption is unavailable and the supply is taxable as food-related job work at 5 per cent.
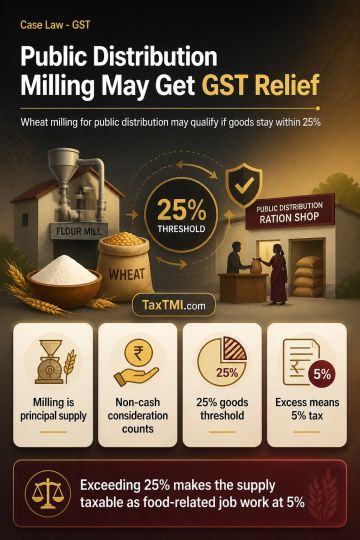
Composite supply of milling allocated wheat, fortifying the flour and packing it for Public Distribution System delivery has milling as its principal supply; fortification and packaging are ancillary. Total consideration includes cash and agreed non-cash consideration represented by retained gunny bags, bran and refractor, rather than their future disposal proceeds. Where goods used for fortification and packing remain within 25 per cent of total composite-supply value, the supply to the State Government qualifies for Serial No. 3A exemption because it relates to public distribution, a function under Article 243G. If the goods component exceeds that threshold, exemption is unavailable and the supply is taxable as food-related job work at 5 per cent.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI