Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
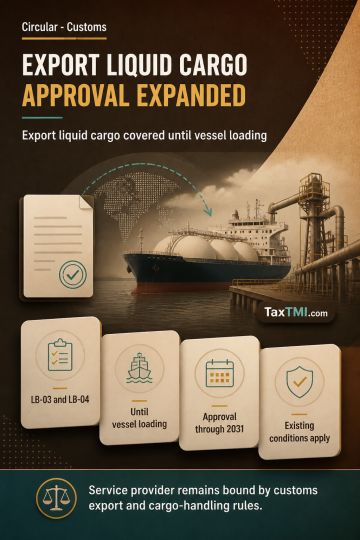
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
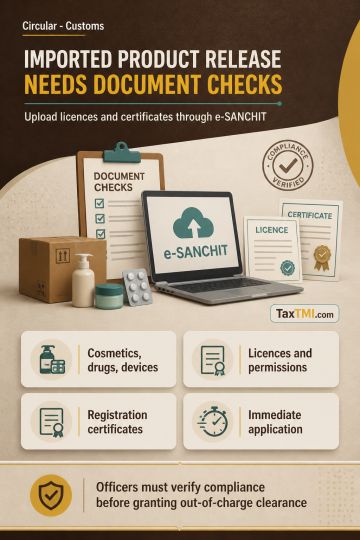
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Double taxation of turnover requires holistic verification across separately registered units and permits limited rectification of overlapping assessm...
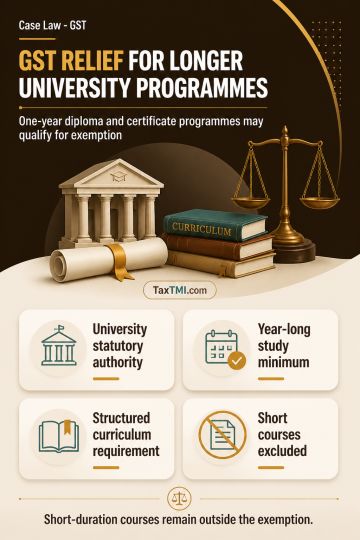
GST exemption for educational services applies to fees charged by a statutory university for diploma and certificate programmes of one year or more where the programmes form part of a structured curriculum leading to qualifications recognised by law. Statutory authority to institute diplomas and certificates and prescribe their academic content supports recognition of long-duration qualifications. Fees for short-duration diploma or certificate courses do not qualify for exemption because they do not meet the requirement of education forming part of a curriculum leading to a legally recognised qualification.
GST exemption for educational services applies to fees charged by a statutory university for diploma and certificate programmes of one year or more where the programmes form part of a structured curriculum leading to qualifications recognised by law. Statutory authority to institute diplomas and certificates and prescribe their academic content supports recognition of long-duration qualifications. Fees for short-duration diploma or certificate courses do not qualify for exemption because they do not meet the requirement of education forming part of a curriculum leading to a legally recognised qualification.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927