Centralised assessment transfers after searches coordinate connected investigations without finally determining the assessee's tax liability or assess...
Unsigned third-party records cannot establish on-money payments without corroboration and cross-examination, requiring deletion of the related additio...
Service-tax exemptions for railway and Government works restrict de novo reassessment, while unsupported limitation and consultation failures invalida...
Page of 4929
Press 'Enter' after typing page number.
101 to 120 of 98580 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
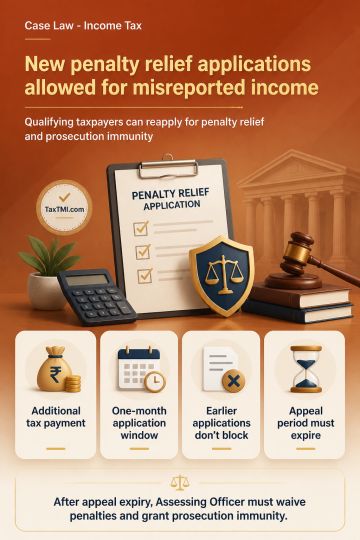
Amended section 270AA permits waiver applications for penalties imposed for under-reporting arising from misreporting of income, subject to payment of the prescribed additional income tax. The earlier exclusion of misreporting cases does not govern applications under the amended regime. Receipt of a penalty order creates a fresh statutory right to apply within one month from the end of the month of receipt, notwithstanding an earlier application under the former provision. Where the statutory conditions are fulfilled and the applicable appeal period has expired, the Assessing Officer must waive the penalty and grant immunity from specified prosecution proceedings.
Amended section 270AA permits waiver applications for penalties imposed for under-reporting arising from misreporting of income, subject to payment of the prescribed additional income tax. The earlier exclusion of misreporting cases does not govern applications under the amended regime. Receipt of a penalty order creates a fresh statutory right to apply within one month from the end of the month of receipt, notwithstanding an earlier application under the former provision. Where the statutory conditions are fulfilled and the applicable appeal period has expired, the Assessing Officer must waive the penalty and grant immunity from specified prosecution proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929