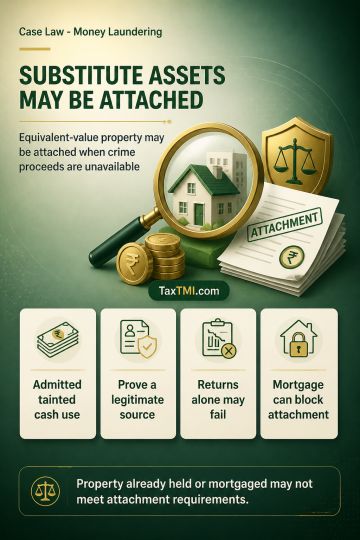
Under the PMLA, property equivalent in value to unavailable proceeds of crime may be attached without a direct nexus to the offence where receipt and expenditure of tainted cash are admitted; statements recorded under Section 50 may support that conclusion if unretracted and corroborated. Holders, including non-accused persons, bear the burden of proving a legitimate source of acquisition; income-tax returns or unsupported claims do not discharge it, although capital-account withdrawals must be considered. Provisional attachment also requires a reasoned apprehension of concealment, transfer or dealing that could frustrate confiscation; property already in investigative custody or subject to a bank mortgage may not satisfy that condition. Recorded reasons and consideration of objections support a valid attachment process.
Under the PMLA, property equivalent in value to unavailable proceeds of crime may be attached without a direct nexus to the offence where receipt and expenditure of tainted cash are admitted; statements recorded under Section 50 may support that conclusion if unretracted and corroborated. Holders, including non-accused persons, bear the burden of proving a legitimate source of acquisition; income-tax returns or unsupported claims do not discharge it, although capital-account withdrawals must be considered. Provisional attachment also requires a reasoned apprehension of concealment, transfer or dealing that could frustrate confiscation; property already in investigative custody or subject to a bank mortgage may not satisfy that condition. Recorded reasons and consideration of objections support a valid attachment process.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897