Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
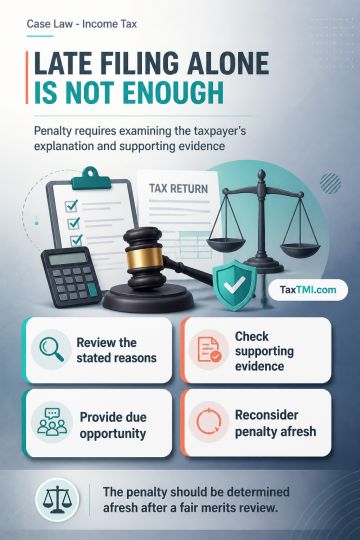
Delayed furnishing of a statement of financial transactions may attract penalty, but belated filing alone does not exclude the statutory defence of reasonable cause. Penalty should not be sustained without examining the taxpayer's explanation and supporting evidence for the delay. Where the first appellate authority has dismissed the matter without deciding the grounds on merits or considering reasonable cause, it should provide due opportunity, examine that defence, and determine the penalty afresh in accordance with law.
Delayed furnishing of a statement of financial transactions may attract penalty, but belated filing alone does not exclude the statutory defence of reasonable cause. Penalty should not be sustained without examining the taxpayer's explanation and supporting evidence for the delay. Where the first appellate authority has dismissed the matter without deciding the grounds on merits or considering reasonable cause, it should provide due opportunity, examine that defence, and determine the penalty afresh in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896