Service-tax exemptions for railway and Government works restrict de novo reassessment, while unsupported limitation and consultation failures invalida...
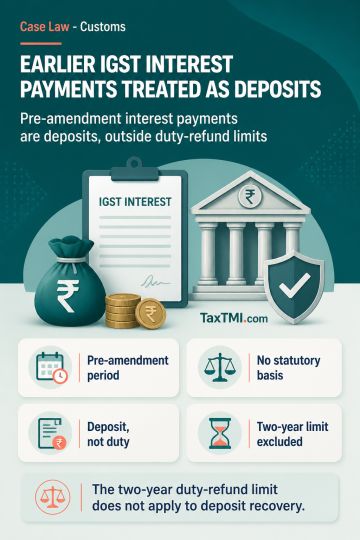
Interest on delayed IGST payment under the Advance Authorisation Scheme for the period preceding legislative amendment lacked a specific statutory basis. The applicable High Court view is to be followed under judicial discipline despite contrary Tribunal views and a pending Larger Bench reference. Interest paid without statutory authority is characterised as a deposit rather than duty. Accordingly, the two-year limitation applicable to duty-refund claims does not govern recovery of that deposit.
Interest on delayed IGST payment under the Advance Authorisation Scheme for the period preceding legislative amendment lacked a specific statutory basis. The applicable High Court view is to be followed under judicial discipline despite contrary Tribunal views and a pending Larger Bench reference. Interest paid without statutory authority is characterised as a deposit rather than duty. Accordingly, the two-year limitation applicable to duty-refund claims does not govern recovery of that deposit.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931