Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
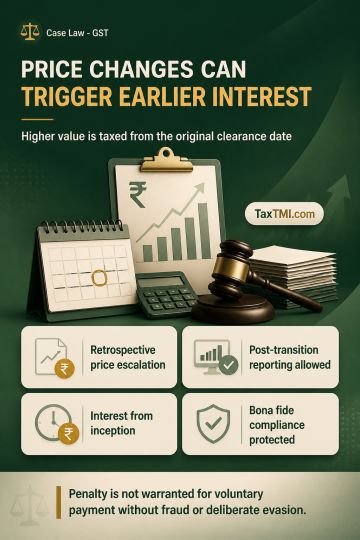
Retrospective contractual price escalation fixes the true value of pre-GST clearances from their original clearance date. Section 142(2)(a) permits GST-compliant debit notes and post-transition reporting of differential tax, but does not create a new taxable event or defer accrual of the enhanced value. Differential tax on the increased value is therefore due from inception, making statutory interest mandatory despite the absence of formal provisional assessment. Penalty under section 122 is not warranted where the differential tax is voluntarily paid after price finalisation under a bona fide understanding of complex transitional provisions, without suppression, fraud, wilful misstatement or deliberate evasion.
Retrospective contractual price escalation fixes the true value of pre-GST clearances from their original clearance date. Section 142(2)(a) permits GST-compliant debit notes and post-transition reporting of differential tax, but does not create a new taxable event or defer accrual of the enhanced value. Differential tax on the increased value is therefore due from inception, making statutory interest mandatory despite the absence of formal provisional assessment. Penalty under section 122 is not warranted where the differential tax is voluntarily paid after price finalisation under a bona fide understanding of complex transitional provisions, without suppression, fraud, wilful misstatement or deliberate evasion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894