Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Quasi-judicial disposal of GST appeals requires hearing and reasoned orders, barring mechanical rejection through system-generated acknowledgements.
    Statutory limits on GST appeal delays remain binding, but restored registrations left departmental challenges without effective relief.
    Self-generated trademark sale proceeds escape capital gains where acquisition cost remains unascertainable, defeating related concealment penalty.
    Foreign contribution registration requires truthful religious-status disclosure and creates no vested right to receive funds.
    Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
    Settlement immunity limits do not prevent inherent powers from quashing abusive post-settlement tax-search prosecutions where appropriate.
    Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
    Misreporting penalties require independent proof; a disallowed political contribution deduction alone cannot establish false particulars.
    Misreporting penalties require evidence of misrepresentation or suppression; incomplete documentation for disclosed improvement costs cannot justify t...
    Transfer-pricing comparability requires exclusion of high-scale branded software companies and LIBOR benchmarking for delayed foreign-currency receiva...
    Section 50C coverage of tenancy-right transfers extends stamp valuation rules, subject to DVO review where fair-market-value objections arise.
    Surviving reassessment limitation period governs validity of fresh notice after deemed notice, preventing expired jurisdiction.
    Accrued unpaid profit-sharing liability remains deductible when obligation has crystallised despite insufficient funds at year-end
    Unaccounted trading sales: Only estimated profit, not gross turnover or duplicated business expenditure, is taxable.
    Pre-amendment investment fund losses pass to eligible unit holders for proportionate carry-forward, subject to factual verification.
    Cessation of trading liabilities requires an actual benefit, while advance-tax interest follows tax on returned income.
    Provisional release security cannot pre-empt unverified penalties, while detained imported goods receive complete demurrage waiver protection.
    Customs classification of CKD electric two-wheeler kits turns on essential character, limiting exemptions where required components are absent.
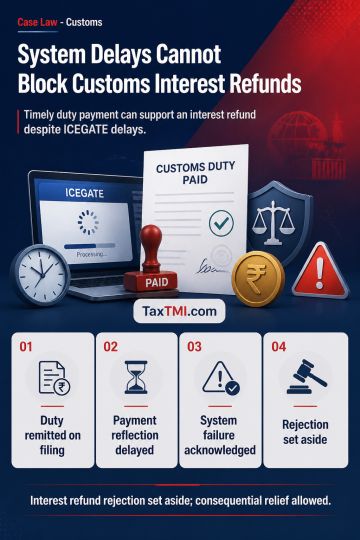
    ICEGATE technical glitches cannot defeat customs interest refunds where duty was timely remitted but payment reflection was delayed.
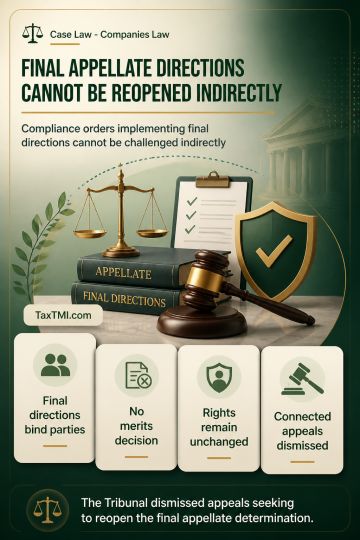
    Binding appellate directions prevent challenges to consequential compliance orders that neither decide merits nor alter parties' rights.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Departmental GST appeals challenging only a penalty must assess...

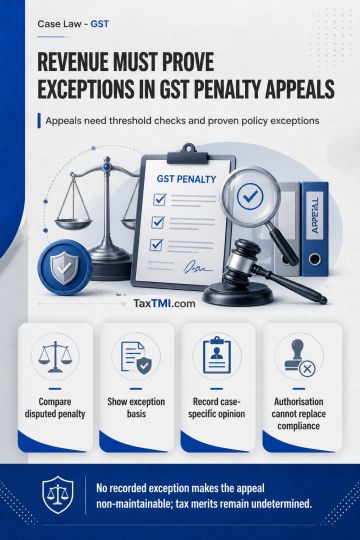
Monetary-limit policy requires Revenue to prove a recognised exception before pursuing a GST penalty appeal on merits.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

GST October 9, 2026 Case Laws AT
Departmental GST appeals challenging only a penalty must assess the disputed penalty against the applicable monetary threshold under the departmental litigation policy. An exception to that policy must be specifically identified and supported by the relevant facts and basis; it cannot be presumed. Commissioner authorisation to file an appeal under section 112(3) does not independently establish an exception or dispense with compliance with the monetary-limit policy. Absence of material showing a recorded case-specific opinion under a residual exception makes the appeal non-maintainable, without determination of the underlying tax merits.

Topics

Acts Income Tax