Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
Disciplinary proportionality requires penalties for Authorised Representative misconduct to match proven harm, leading to reconsideration of registrat...
Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
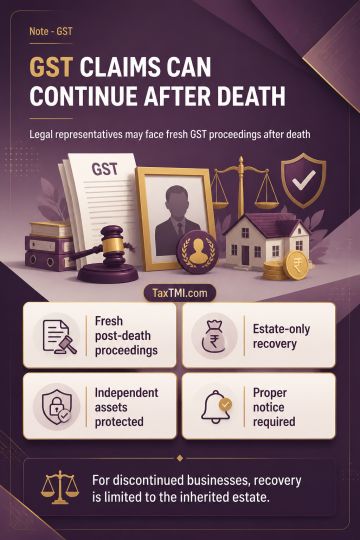
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Page of 4935
Press 'Enter' after typing page number.
381 to 400 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
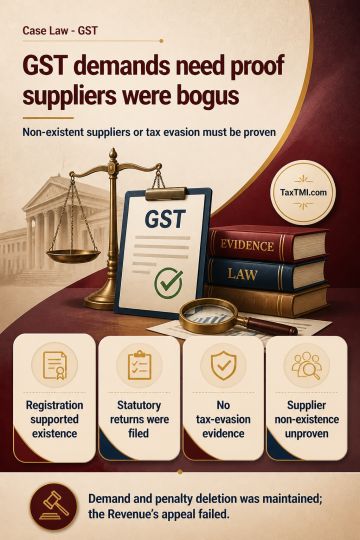
GST demands alleging bogus inward supplies require proof that the supplier firm was non-existent or that tax evasion occurred. Registration of the firm and filing of relevant statutory returns supported its existence. In the absence of evidence disproving those facts or establishing tax evasion, the allegation of a bogus or non-existent firm could not sustain the GST demand or penalty. The deletion of the demand and penalty was consequently maintained, and the Revenue's appeal failed.
GST demands alleging bogus inward supplies require proof that the supplier firm was non-existent or that tax evasion occurred. Registration of the firm and filing of relevant statutory returns supported its existence. In the absence of evidence disproving those facts or establishing tax evasion, the allegation of a bogus or non-existent firm could not sustain the GST demand or penalty. The deletion of the demand and penalty was consequently maintained, and the Revenue's appeal failed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935