Unsigned third-party records cannot establish on-money payments without corroboration and cross-examination, requiring deletion of the related additio...
Service-tax exemptions for railway and Government works restrict de novo reassessment, while unsupported limitation and consultation failures invalida...
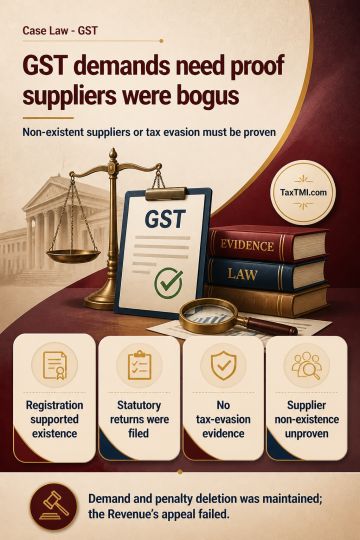
GST demands alleging bogus inward supplies require proof that the supplier firm was non-existent or that tax evasion occurred. Registration of the firm and filing of relevant statutory returns supported its existence. In the absence of evidence disproving those facts or establishing tax evasion, the allegation of a bogus or non-existent firm could not sustain the GST demand or penalty. The deletion of the demand and penalty was consequently maintained, and the Revenue's appeal failed.
GST demands alleging bogus inward supplies require proof that the supplier firm was non-existent or that tax evasion occurred. Registration of the firm and filing of relevant statutory returns supported its existence. In the absence of evidence disproving those facts or establishing tax evasion, the allegation of a bogus or non-existent firm could not sustain the GST demand or penalty. The deletion of the demand and penalty was consequently maintained, and the Revenue's appeal failed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935