Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
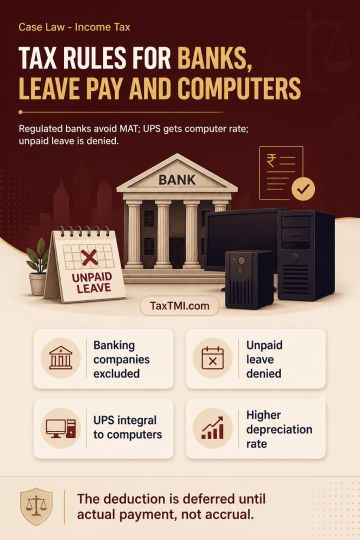
Minimum alternate tax does not apply to a banking company governed by the Banking Regulation Act, 1949. Leave-salary or leave-encashment liability may accrue under mercantile accounting, but its deduction is deferred until actual payment; an unpaid provision is not deductible. An uninterrupted power supply used solely to support a computer system, without evidence of independent use, forms an integral part of that system and qualifies for depreciation at the computer-equipment rate. The tax treatment therefore excludes regulated banking companies from minimum alternate tax and allows the higher computer-equipment depreciation rate, while denying deduction for unpaid leave-encashment provisions.
Minimum alternate tax does not apply to a banking company governed by the Banking Regulation Act, 1949. Leave-salary or leave-encashment liability may accrue under mercantile accounting, but its deduction is deferred until actual payment; an unpaid provision is not deductible. An uninterrupted power supply used solely to support a computer system, without evidence of independent use, forms an integral part of that system and qualifies for depreciation at the computer-equipment rate. The tax treatment therefore excludes regulated banking companies from minimum alternate tax and allows the higher computer-equipment depreciation rate, while denying deduction for unpaid leave-encashment provisions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894