Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
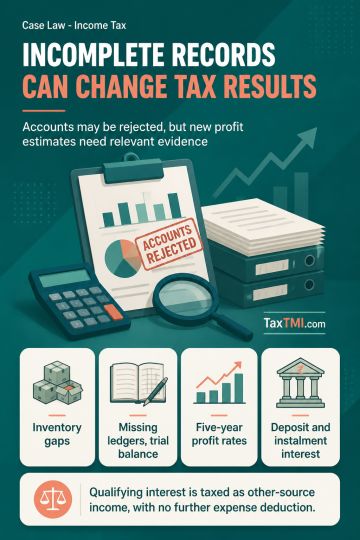
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Minimum alternate tax does not apply to a banking company governed by the Banking Regulation Act, 1949. Leave-salary or leave-encashment liability may accrue under mercantile accounting, but its deduction is deferred until actual payment; an unpaid provision is not deductible. An uninterrupted power supply used solely to support a computer system, without evidence of independent use, forms an integral part of that system and qualifies for depreciation at the computer-equipment rate. The tax treatment therefore excludes regulated banking companies from minimum alternate tax and allows the higher computer-equipment depreciation rate, while denying deduction for unpaid leave-encashment provisions.
Minimum alternate tax does not apply to a banking company governed by the Banking Regulation Act, 1949. Leave-salary or leave-encashment liability may accrue under mercantile accounting, but its deduction is deferred until actual payment; an unpaid provision is not deductible. An uninterrupted power supply used solely to support a computer system, without evidence of independent use, forms an integral part of that system and qualifies for depreciation at the computer-equipment rate. The tax treatment therefore excludes regulated banking companies from minimum alternate tax and allows the higher computer-equipment depreciation rate, while denying deduction for unpaid leave-encashment provisions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931