Disciplinary proportionality requires penalties for Authorised Representative misconduct to match proven harm, leading to reconsideration of registrat...
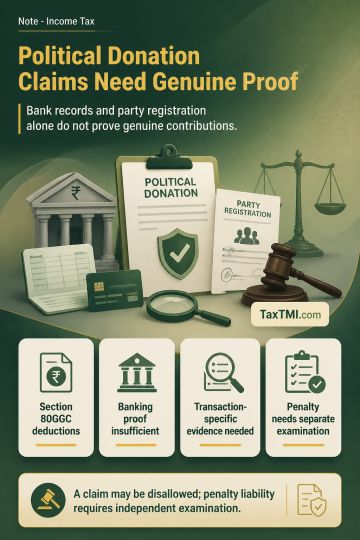
Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
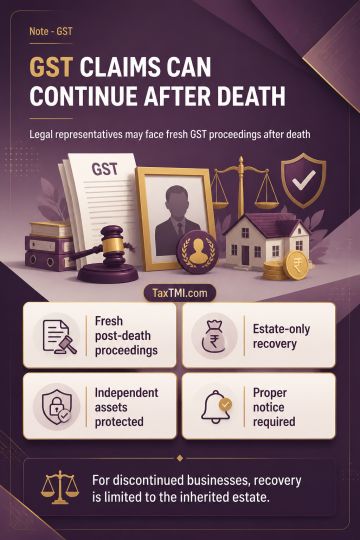
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
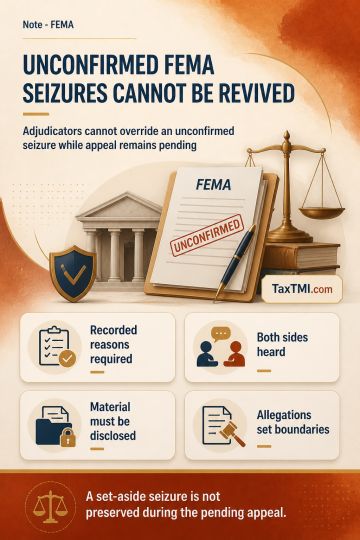
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
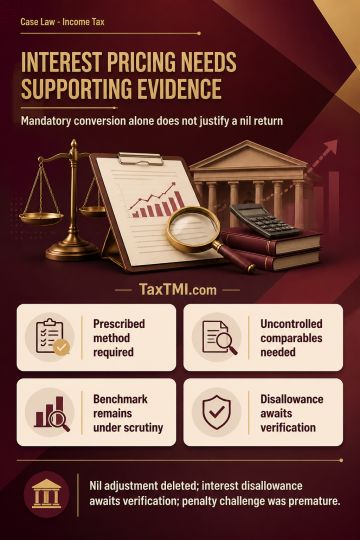
Compulsorily convertible debentures do not warrant a nil arm's length price for pre-conversion coupon interest merely because conversion is mandatory and cash redemption is unavailable. Recharacterisation of debt requires contractual and economic facts showing divergence between form and substance or commercial irrationality, and a nil return must be supported by a prescribed transfer-pricing method and uncontrolled comparables. The nil transfer-pricing adjustment was deleted, while the proposed domestic benchmark remained subject to scrutiny. The related interest disallowance was set aside pending verification of capitalisation, business use and interest-limitation treatment, without double deduction or double disallowance. Consequential statutory interest or fees must identify the charging provision, period and calculation; a penalty challenge remains premature before a penalty order.
Compulsorily convertible debentures do not warrant a nil arm's length price for pre-conversion coupon interest merely because conversion is mandatory and cash redemption is unavailable. Recharacterisation of debt requires contractual and economic facts showing divergence between form and substance or commercial irrationality, and a nil return must be supported by a prescribed transfer-pricing method and uncontrolled comparables. The nil transfer-pricing adjustment was deleted, while the proposed domestic benchmark remained subject to scrutiny. The related interest disallowance was set aside pending verification of capitalisation, business use and interest-limitation treatment, without double deduction or double disallowance. Consequential statutory interest or fees must identify the charging provision, period and calculation; a penalty challenge remains premature before a penalty order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931