Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
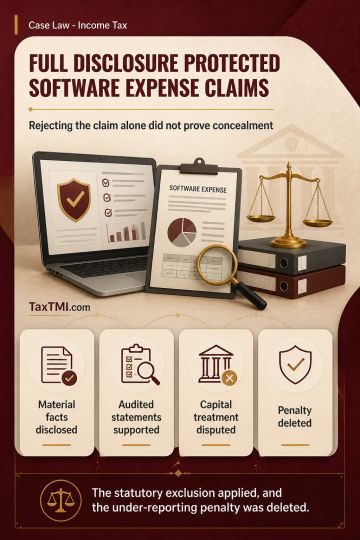
Section 270A excludes an amount from under-reported income where the taxpayer gives a bona fide explanation and fully discloses material facts needed to support it. Rejection of a claim in quantum proceedings does not itself establish false particulars, concealment, or lack of bona fides. Software-development expenditure and its accounting treatment disclosed in audited financial statements may therefore remain eligible for exclusion where the dispute concerns the debatable legal characterisation of the expenditure as revenue expenditure or capital loss. On the stated facts, the statutory exclusion applied and the penalty was deleted.
Section 270A excludes an amount from under-reported income where the taxpayer gives a bona fide explanation and fully discloses material facts needed to support it. Rejection of a claim in quantum proceedings does not itself establish false particulars, concealment, or lack of bona fides. Software-development expenditure and its accounting treatment disclosed in audited financial statements may therefore remain eligible for exclusion where the dispute concerns the debatable legal characterisation of the expenditure as revenue expenditure or capital loss. On the stated facts, the statutory exclusion applied and the penalty was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937