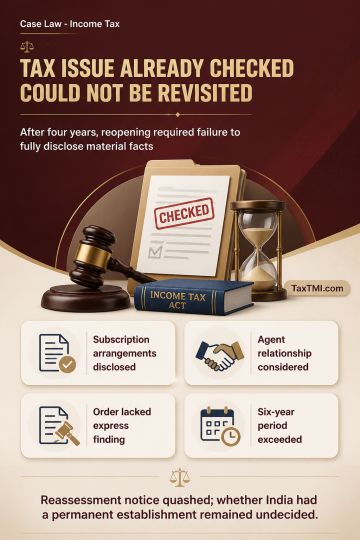
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
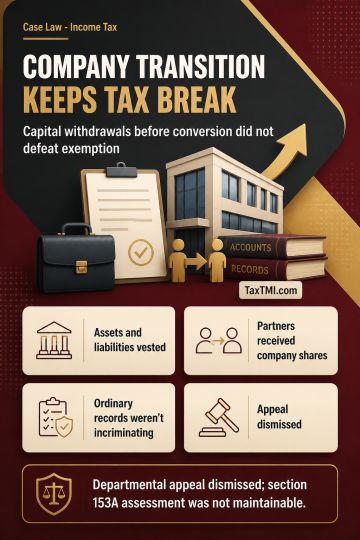
Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
Listed Central Excise and Service Tax appeals filed on or after 1 July 2017 are reassigned, in partial modification of the earlier allocation order, to the designated Commissioners of the Kolkata Appeal-II and Howrah Commissionerates. The reassignment covers the appeals identified in the annexure for disposal through Orders-in-Appeal under the Central Excise Act, 1944 or the Finance Act, 1994, as applicable. It governs pre-GST matters concerning acts or omissions before the Central Goods and Services Tax Act, 2017 came into force.
Listed Central Excise and Service Tax appeals filed on or after 1 July 2017 are reassigned, in partial modification of the earlier allocation order, to the designated Commissioners of the Kolkata Appeal-II and Howrah Commissionerates. The reassignment covers the appeals identified in the annexure for disposal through Orders-in-Appeal under the Central Excise Act, 1944 or the Finance Act, 1994, as applicable. It governs pre-GST matters concerning acts or omissions before the Central Goods and Services Tax Act, 2017 came into force.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918