Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangemen...
Mobile-phone electronic evidence failed to establish customs undervaluation, while duty survived on non-authentic origin certificates without importer...
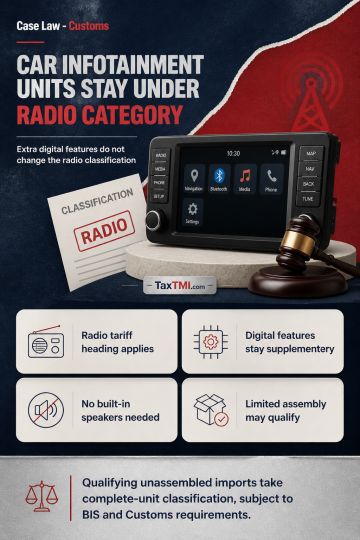
Automotive radio classification treats integrated infotainment features as supplementary, placing complete and qualifying unassembled units under the ...
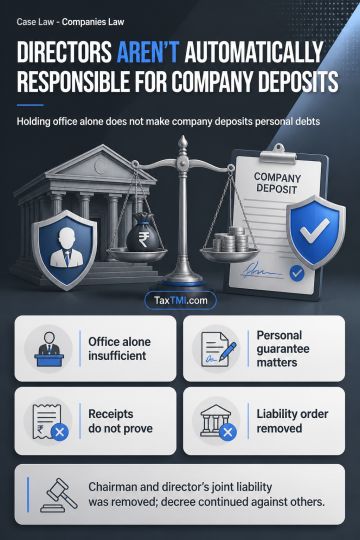
Separate corporate personality prevents directors from being personally liable for company deposits without a guarantee or independent legal undertaki...
Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
Income Declaration Scheme declarations provide personal immunity...
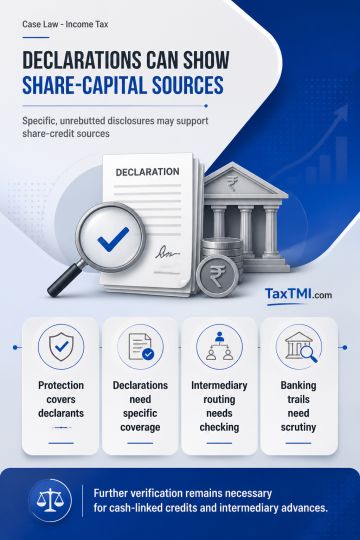
Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verification.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Income Declaration Scheme declarations provide personal immunity only to declarants, but an accepted, tax-paid declaration may evidence the true source of share-capital and share-premium credits in another taxpayer's books where it specifically covers the credits and remains unrebutted; taxing that same income again risks double taxation. Before the source-of-source proviso applied, the taxpayer's burden for such credits was limited to identity, genuineness and creditworthiness, although apparent routing of its own advances through intermediaries required verification of commercial rationale. A banking trail alone does not exclude prior cash funding, requiring examination of relevant admissions. A search statement directly linking accommodation entries to the taxpayer supplies tangible material for a reason to believe; objections need not be disposed of in a separate speaking order where recorded reasons independently sustain jurisdiction.
Income Declaration Scheme declarations provide personal immunity only to declarants, but an accepted, tax-paid declaration may evidence the true source of share-capital and share-premium credits in another taxpayer's books where it specifically covers the credits and remains unrebutted; taxing that same income again risks double taxation. Before the source-of-source proviso applied, the taxpayer's burden for such credits was limited to identity, genuineness and creditworthiness, although apparent routing of its own advances through intermediaries required verification of commercial rationale. A banking trail alone does not exclude prior cash funding, requiring examination of relevant admissions. A search statement directly linking accommodation entries to the taxpayer supplies tangible material for a reason to believe; objections need not be disposed of in a separate speaking order where recorded reasons independently sustain jurisdiction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927