Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Double taxation of turnover requires holistic verification across separately registered units and permits limited rectification of overlapping assessm...
In faceless assessments involving a reference to the Valuation...
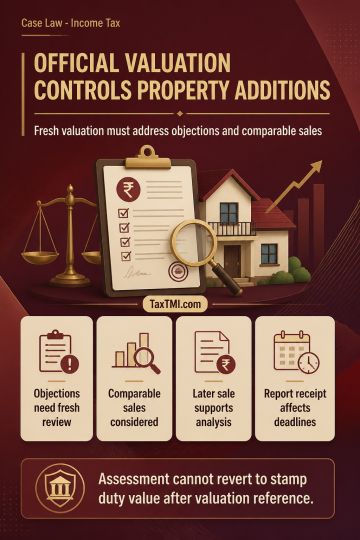
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and comparables.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
In faceless assessments involving a reference to the Valuation Officer, limitation is computed by reference to the Assessment Unit's receipt of the report through the prescribed channel, not merely the assessee's emailed copy. Exclusion of the reference period and the statutory extension of the remaining period can preserve the assessment's timeliness. For property acquired below stamp duty value, once the statutory valuation process is invoked, assessment must conform to the Valuation Officer's estimate rather than revert to stamp duty value. Methodology objections, comparable sales, independent valuation evidence and a subsequent sale require consideration in a fresh valuation, although later sale evidence is corroborative rather than determinative.
In faceless assessments involving a reference to the Valuation Officer, limitation is computed by reference to the Assessment Unit's receipt of the report through the prescribed channel, not merely the assessee's emailed copy. Exclusion of the reference period and the statutory extension of the remaining period can preserve the assessment's timeliness. For property acquired below stamp duty value, once the statutory valuation process is invoked, assessment must conform to the Valuation Officer's estimate rather than revert to stamp duty value. Methodology objections, comparable sales, independent valuation evidence and a subsequent sale require consideration in a fresh valuation, although later sale evidence is corroborative rather than determinative.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937