Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
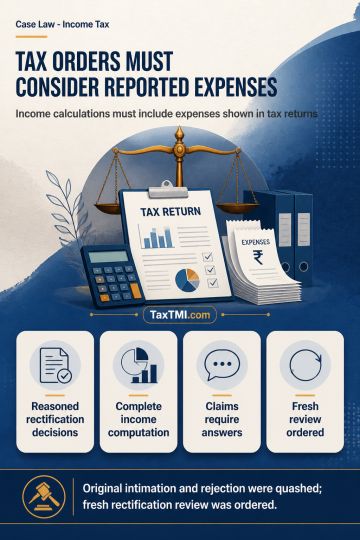
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
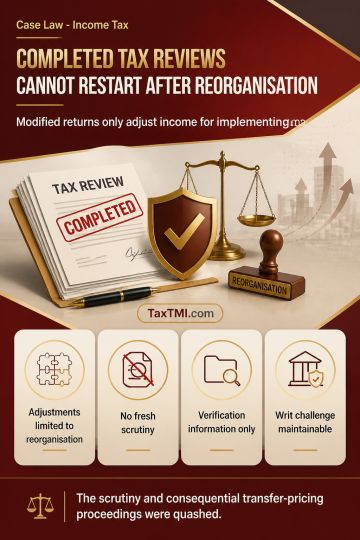
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Judicial declarations invalidating the reverse-charge IGST levy...
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal grounds.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Judicial declarations invalidating the reverse-charge IGST levy on imported ocean freight operate retrospectively unless expressly limited, rendering the levy void from inception. Taxpayers who were not parties to the invalidating proceedings may rely on that declaration for refunds, except where their own unsuccessful challenge to the levy has attained finality. A departmental representative may challenge only grounds authorised by the Commissioner. Utilisation of IGST credit does not by itself create double benefit or unjust enrichment where unutilised CGST and SGST credits of equivalent value can be debited. Refunds are therefore supportable, with statutory interest for delay.
Judicial declarations invalidating the reverse-charge IGST levy on imported ocean freight operate retrospectively unless expressly limited, rendering the levy void from inception. Taxpayers who were not parties to the invalidating proceedings may rely on that declaration for refunds, except where their own unsuccessful challenge to the levy has attained finality. A departmental representative may challenge only grounds authorised by the Commissioner. Utilisation of IGST credit does not by itself create double benefit or unjust enrichment where unutilised CGST and SGST credits of equivalent value can be debited. Refunds are therefore supportable, with statutory interest for delay.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891