Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
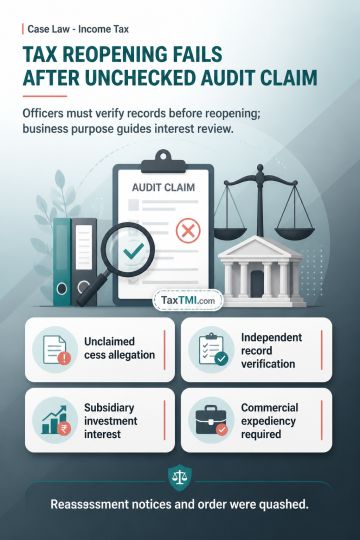
Reassessment founded on an audit objection requires the Assessing Officer to verify the record and independently apply mind. An allegation that health and education cess had been deducted could not support reassessment where no such deduction was claimed and the audit premise was unverified. Interest on borrowed funds invested in a subsidiary must be assessed through commercial expediency from a prudent businessperson's standpoint; reassessment could not proceed where that governing principle was not distinguished on recorded facts. The reassessment notices and order were quashed.
Reassessment founded on an audit objection requires the Assessing Officer to verify the record and independently apply mind. An allegation that health and education cess had been deducted could not support reassessment where no such deduction was claimed and the audit premise was unverified. Interest on borrowed funds invested in a subsidiary must be assessed through commercial expediency from a prudent businessperson's standpoint; reassessment could not proceed where that governing principle was not distinguished on recorded facts. The reassessment notices and order were quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894