Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
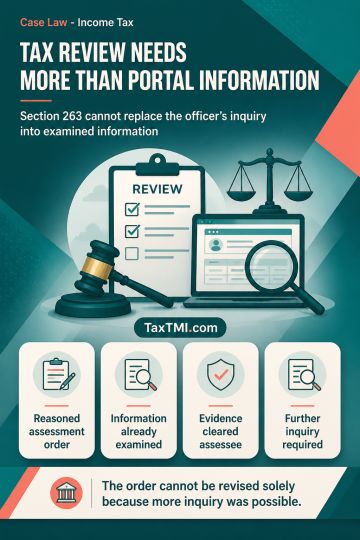
Revisional jurisdiction under section 263 requires an assessment order to be both erroneous and prejudicial to Revenue interests. Revision cannot rest merely on Insight Portal information that the Assessing Officer already examined during reassessment, where the officer considered explanations and supporting evidence showing that the alleged accommodation-entry transactions did not concern the assessee. The revisional authority must identify discrepancies in the material examined or conduct further inquiry; it cannot substitute its view merely because additional inquiry was possible. Sufficient inquiry by the Assessing Officer distinguishes an impermissible review for allegedly inadequate inquiry from a valid revision based on lack of inquiry.
Revisional jurisdiction under section 263 requires an assessment order to be both erroneous and prejudicial to Revenue interests. Revision cannot rest merely on Insight Portal information that the Assessing Officer already examined during reassessment, where the officer considered explanations and supporting evidence showing that the alleged accommodation-entry transactions did not concern the assessee. The revisional authority must identify discrepancies in the material examined or conduct further inquiry; it cannot substitute its view merely because additional inquiry was possible. Sufficient inquiry by the Assessing Officer distinguishes an impermissible review for allegedly inadequate inquiry from a valid revision based on lack of inquiry.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI