Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
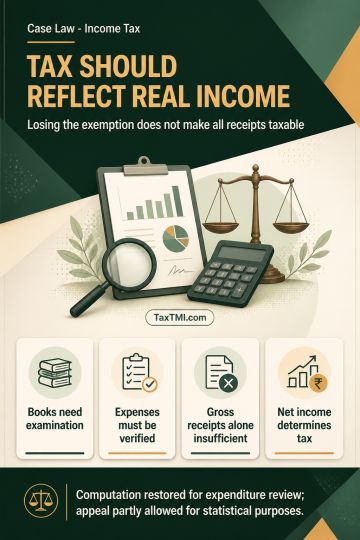
Denial of charitable exemption under section 11 does not by itself justify taxing an educational trust's entire gross receipts. Taxable income must ordinarily reflect real income, determined after verification and allowance of genuine expenditure otherwise admissible in law, unless a provision requires taxation on a gross basis. The computation was restored to the assessing authority to examine the books and determine net taxable income after verifying the claimed expenditure; the appeal was partly allowed for statistical purposes.
Denial of charitable exemption under section 11 does not by itself justify taxing an educational trust's entire gross receipts. Taxable income must ordinarily reflect real income, determined after verification and allowance of genuine expenditure otherwise admissible in law, unless a provision requires taxation on a gross basis. The computation was restored to the assessing authority to examine the books and determine net taxable income after verifying the claimed expenditure; the appeal was partly allowed for statistical purposes.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927