Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
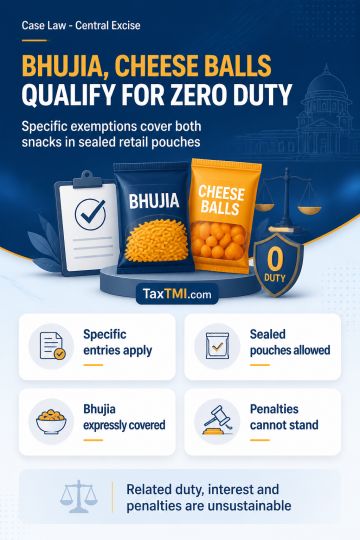
Specific nil-rate exemption entries for namkeen and similar edible preparations apply to Cheese Balls and Bhujia cleared in sealed retail pouches. Cheese Balls fall within the specific entry for similar ready-to-consume edible preparations, while the residual packaged-food entry applies only where no specific description covers the goods; sealed packaging does not displace the specific exemption. Bhujia is expressly covered by a separate specific entry, and its sealed-container restriction cannot be imported from a differently worded residual entry. Classification under Tariff Item 2106 90 99 remains within sub-heading 2106 90, so it does not exclude eligibility where the exemption refers to that sub-heading. Nil-rate treatment consequently applies and related duty, interest and penalties are unsustainable.
Specific nil-rate exemption entries for namkeen and similar edible preparations apply to Cheese Balls and Bhujia cleared in sealed retail pouches. Cheese Balls fall within the specific entry for similar ready-to-consume edible preparations, while the residual packaged-food entry applies only where no specific description covers the goods; sealed packaging does not displace the specific exemption. Bhujia is expressly covered by a separate specific entry, and its sealed-container restriction cannot be imported from a differently worded residual entry. Classification under Tariff Item 2106 90 99 remains within sub-heading 2106 90, so it does not exclude eligibility where the exemption refers to that sub-heading. Nil-rate treatment consequently applies and related duty, interest and penalties are unsustainable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927