Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
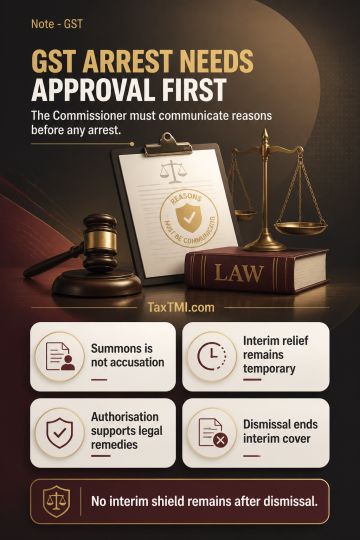
Interim protection from arrest cannot survive dismissal of an anticipatory-bail application as not maintainable, because interim relief must remain ancillary to a pending substantive proceeding. Under the GST arrest framework, a summons does not itself make a person an accused or create a legally sustainable apprehension of arrest. Arrest requires the Commissioner's reasoned authorisation based on reasons to believe that a specified offence has been committed. That authorisation must be communicated before arrest, enabling the affected person to pursue anticipatory bail, judicial review, or other available remedies. Communication is a statutory procedural safeguard, not residual bail protection after dismissal.
Interim protection from arrest cannot survive dismissal of an anticipatory-bail application as not maintainable, because interim relief must remain ancillary to a pending substantive proceeding. Under the GST arrest framework, a summons does not itself make a person an accused or create a legally sustainable apprehension of arrest. Arrest requires the Commissioner's reasoned authorisation based on reasons to believe that a specified offence has been committed. That authorisation must be communicated before arrest, enabling the affected person to pursue anticipatory bail, judicial review, or other available remedies. Communication is a statutory procedural safeguard, not residual bail protection after dismissal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888