Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
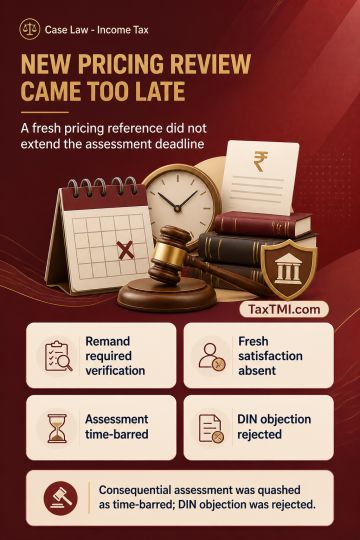
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Section 87A, as applicable to the relevant assessment year, allows a resident individual under the concessional regime to claim a rebate from income-tax on total income, including tax computed on qualifying short-term capital gains under section 111A, where the prescribed conditions are met. Section 111A fixes the special-rate computation for those gains but does not expressly exclude the resulting tax from the rebate base. Section 115BAC(1A) preserves Chapter XII special-rate computation and does not displace the separate rebate. By contrast, section 112A(6) expressly limits rebate against tax on specified long-term capital gains. Eligibility remains dependent on assessment-year-specific statutory text, resident status, applicable income limit, and any express restriction.
Section 87A, as applicable to the relevant assessment year, allows a resident individual under the concessional regime to claim a rebate from income-tax on total income, including tax computed on qualifying short-term capital gains under section 111A, where the prescribed conditions are met. Section 111A fixes the special-rate computation for those gains but does not expressly exclude the resulting tax from the rebate base. Section 115BAC(1A) preserves Chapter XII special-rate computation and does not displace the separate rebate. By contrast, section 112A(6) expressly limits rebate against tax on specified long-term capital gains. Eligibility remains dependent on assessment-year-specific statutory text, resident status, applicable income limit, and any express restriction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932