Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
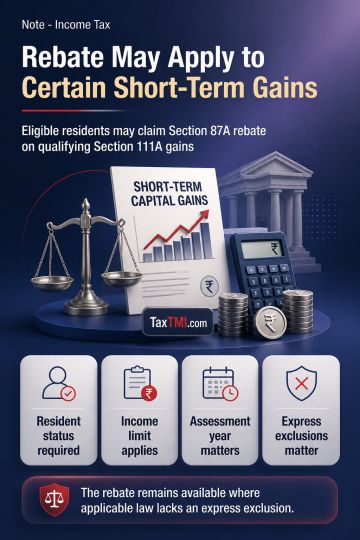
Section 87A, as applicable to the relevant assessment year, allows a resident individual under the concessional regime to claim a rebate from income-tax on total income, including tax computed on qualifying short-term capital gains under section 111A, where the prescribed conditions are met. Section 111A fixes the special-rate computation for those gains but does not expressly exclude the resulting tax from the rebate base. Section 115BAC(1A) preserves Chapter XII special-rate computation and does not displace the separate rebate. By contrast, section 112A(6) expressly limits rebate against tax on specified long-term capital gains. Eligibility remains dependent on assessment-year-specific statutory text, resident status, applicable income limit, and any express restriction.
Section 87A, as applicable to the relevant assessment year, allows a resident individual under the concessional regime to claim a rebate from income-tax on total income, including tax computed on qualifying short-term capital gains under section 111A, where the prescribed conditions are met. Section 111A fixes the special-rate computation for those gains but does not expressly exclude the resulting tax from the rebate base. Section 115BAC(1A) preserves Chapter XII special-rate computation and does not displace the separate rebate. By contrast, section 112A(6) expressly limits rebate against tax on specified long-term capital gains. Eligibility remains dependent on assessment-year-specific statutory text, resident status, applicable income limit, and any express restriction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929