Juridical seat versus arbitral venue determines supervisory court jurisdiction, while timely award challenges remain within the prescribed limitation ...
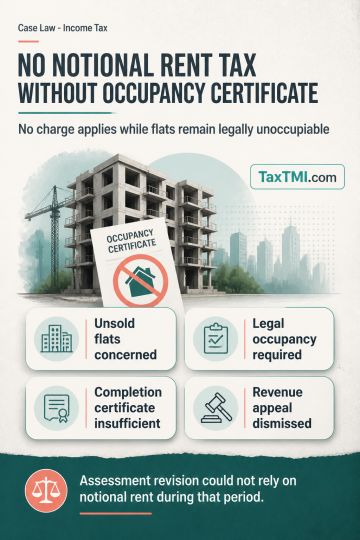
Notional rental income under Section 23(1)(a) is not chargeable on unsold flats during a period in which they are legally unoccupiable because no occupancy certificate has been issued. A completion certificate alone does not establish legal occupiability for this purpose. Consequently, notional rental income cannot form the basis for revision of an assessment for that period, and the Revenue's appeal was dismissed.
Notional rental income under Section 23(1)(a) is not chargeable on unsold flats during a period in which they are legally unoccupiable because no occupancy certificate has been issued. A completion certificate alone does not establish legal occupiability for this purpose. Consequently, notional rental income cannot form the basis for revision of an assessment for that period, and the Revenue's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888