Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
Disciplinary proportionality requires penalties for Authorised Representative misconduct to match proven harm, leading to reconsideration of registrat...
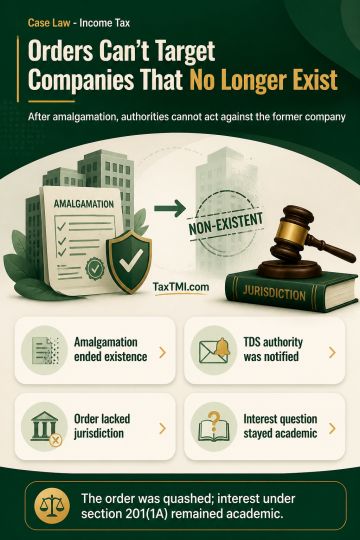
Jurisdiction over an amalgamating company ends when it ceases to exist following amalgamation. A section 201 order issued and served in the former company's name, despite prior notification to the TDS authority, suffers a jurisdictional defect; referring to the successor company in the body of the order does not cure it. The order was void ab initio and quashed, while the issue of interest under section 201(1A) remained academic.
Note: It is a system-generated summary and is for quick reference only.