Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
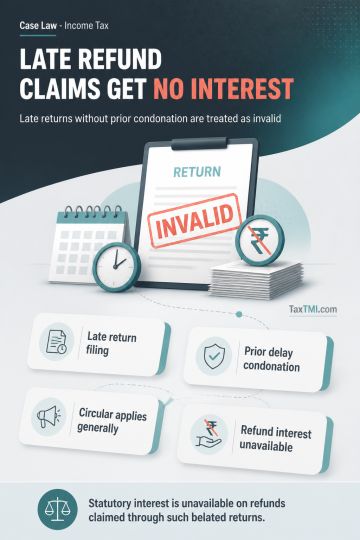
Interest under section 244A on a refund claimed through a return filed after the statutory deadline depends on the return's validity and prior condonation of delay. A return filed late without a preceding condonation application is treated as invalid for this purpose. Clause (ii) of paragraph 6 of the CBDT circular applies generally to belated refund claims, rather than only to supplementary refund claims, when read with the circular's preceding provisions. Statutory interest is therefore unavailable on refunds claimed through such belated returns.
Interest under section 244A on a refund claimed through a return filed after the statutory deadline depends on the return's validity and prior condonation of delay. A return filed late without a preceding condonation application is treated as invalid for this purpose. Clause (ii) of paragraph 6 of the CBDT circular applies generally to belated refund claims, rather than only to supplementary refund claims, when read with the circular's preceding provisions. Statutory interest is therefore unavailable on refunds claimed through such belated returns.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934