Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
Judicial discipline requires consistent reassessment treatment where identical facts were decided for the same taxpayer in the preceding assessment ye...
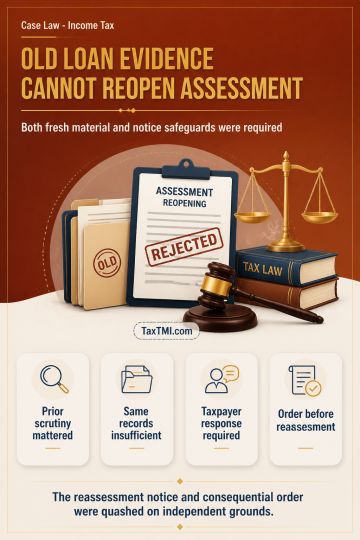
Reassessment of a loan credit previously examined in scrutiny cannot rest on the same confirmation, bank statements and balance sheet without fresh information or tangible material; adopting a different view is an impermissible change of opinion. Separately, an electronic notice served on or after 1 April 2021 must follow section 148A: a show-cause notice, supply of material, consideration of the taxpayer's reply, and an order before issuing a notice under section 148. Failure to follow this sequence invalidates reassessment. On these independent grounds, the reassessment notice and consequential order were quashed, without deciding the loan-credit addition on merits.
Reassessment of a loan credit previously examined in scrutiny cannot rest on the same confirmation, bank statements and balance sheet without fresh information or tangible material; adopting a different view is an impermissible change of opinion. Separately, an electronic notice served on or after 1 April 2021 must follow section 148A: a show-cause notice, supply of material, consideration of the taxpayer's reply, and an order before issuing a notice under section 148. Failure to follow this sequence invalidates reassessment. On these independent grounds, the reassessment notice and consequential order were quashed, without deciding the loan-credit addition on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897