Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
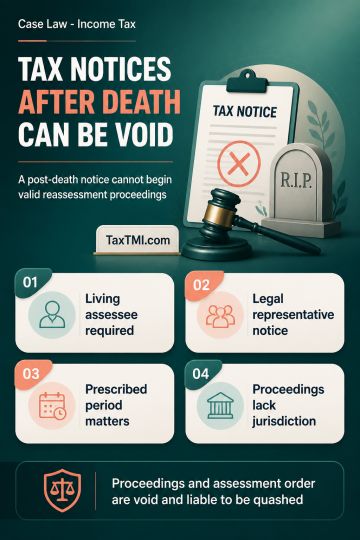
Reassessment proceedings initiated by a notice issued in the name of an assessee already deceased are jurisdictionally defective. A valid reassessment notice must be addressed to a living assessee or, where permitted, to the legal representative. Provisions allowing continuation of existing proceedings against legal representatives do not cure proceedings initiated only after the assessee's death. Where no fresh notice is issued to the legal representatives within the prescribed period, the reassessment lacks jurisdiction. The notice, consequential reassessment proceedings and assessment order are void in law and liable to be quashed.
Reassessment proceedings initiated by a notice issued in the name of an assessee already deceased are jurisdictionally defective. A valid reassessment notice must be addressed to a living assessee or, where permitted, to the legal representative. Provisions allowing continuation of existing proceedings against legal representatives do not cure proceedings initiated only after the assessee's death. Where no fresh notice is issued to the legal representatives within the prescribed period, the reassessment lacks jurisdiction. The notice, consequential reassessment proceedings and assessment order are void in law and liable to be quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891